Property Types to Know
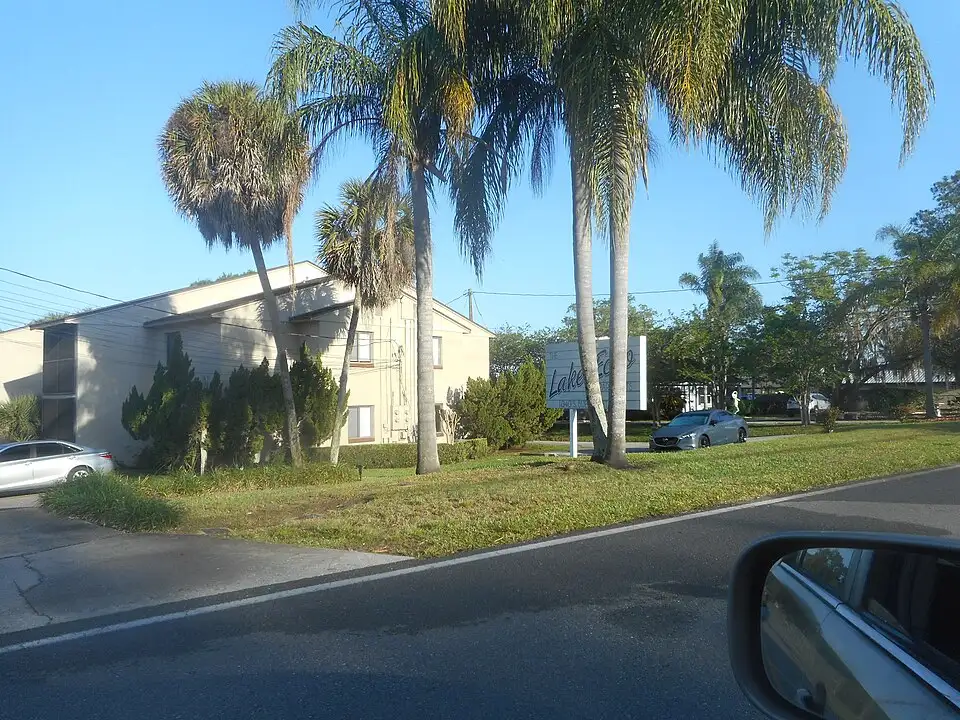
Duplex, triplex, and fourplex properties (2-4 units) are financed differently than anything 5 units and up, which falls under commercial lending rules. Most first-time multi-family investors start in the 2-4 unit range specifically because of the more accessible financing.
Financing a Duplex You Live In
If you plan to live in one unit, an FHA loan can finance a duplex with as little as 3.5 percent down, the same minimum that applies to a single-family home, with a credit score of 580 or higher. FHA requires you to occupy one of the units as your principal residence. Fannie Mae and Freddie Mac conventional loans allow as little as 5 percent down on an owner-occupied two-unit home when the loan gets an automated approval, and manually underwritten loans typically need more. Loans for investors who will not live in the property usually need a larger down payment. County loan limits change every year, so ask me for the current limit for two-unit homes in Orange County.
If You Are Considering a Triplex or Fourplex
FHA also finances three- and four-unit properties, but adds a rental income test: the full monthly payment, including taxes and insurance, cannot exceed the net rental income from all units based on the appraiser's market-rent estimate, and lenders also require cash reserves after closing. That is why a fourplex needs stronger numbers than a duplex even with the same down payment.
Running the Numbers
Before making an offer, we look at gross rental income, realistic vacancy and maintenance reserves, taxes, insurance, and financing costs, to arrive at actual expected cash flow, not just a rough headline number. A property that looks profitable on paper can fall apart once real expenses are accounted for. HUD publishes Fair Market Rents for the Orlando-Kissimmee-Sanford area each fall, which is a useful sanity check, but current rent comparables for the specific street matter more.
Property Taxes Reset When You Buy
Florida resets a property's assessed value to market value after a sale, effective the following January 1, so the seller's tax bill is not a reliable guide to yours. For non-homestead residential property with nine or fewer units, such as a duplex you rent out entirely, annual increases in assessed value are generally capped at 10 percent after that first reset. Build the new tax estimate into your numbers before you make an offer.
Florida Rules for Landlords
If you rent a unit, Florida law sets specific rules. Under Chapter 83, a landlord can serve a three-day notice for unpaid rent, not counting weekends or legal holidays, and a seven-day notice to cure many lease violations. A tenancy with no fixed end date, such as month to month, generally needs 30 days' notice to end. Security deposits must be returned within 15 days if there is no claim, and a claim must be sent within 30 days or it is forfeited. You must also give the Florida radon notice in the lease or sale documents and, for homes built before 1978, the federal lead-based paint disclosure. Have a Florida attorney review your lease and notices.
Short-Term Rentals Are Tightly Limited
Do not count on Airbnb income from an Orlando duplex. The City of Orlando does not allow renting an entire residence for fewer than 30 days; it allows a Home Share, where the owner or tenant lives on site and rents up to half the bedrooms, with registration. One half of a duplex can be home-shared only if both units are on the same lot under one owner and the registrant lives there. In unincorporated Orange County, the county says short-term rentals are not allowed in most residential areas. Rules change, so confirm the current code for the specific address before you rely on short-term income.
Where to Look in Central Florida
Orlando and Azalea Park have a genuine supply of smaller multi-family properties suited to this strategy, with demand from long-term tenants. Altamonte Springs and Casselberry are also worth comparing, depending on your budget and goals.
Scaling Beyond Your First Property
Once your first multi-family property is stabilized, refinancing to pull out equity, or using the income to qualify for your next purchase, are both common paths to growing a portfolio. We'll talk through the right next step once you're there.